Alamat
Malaysia
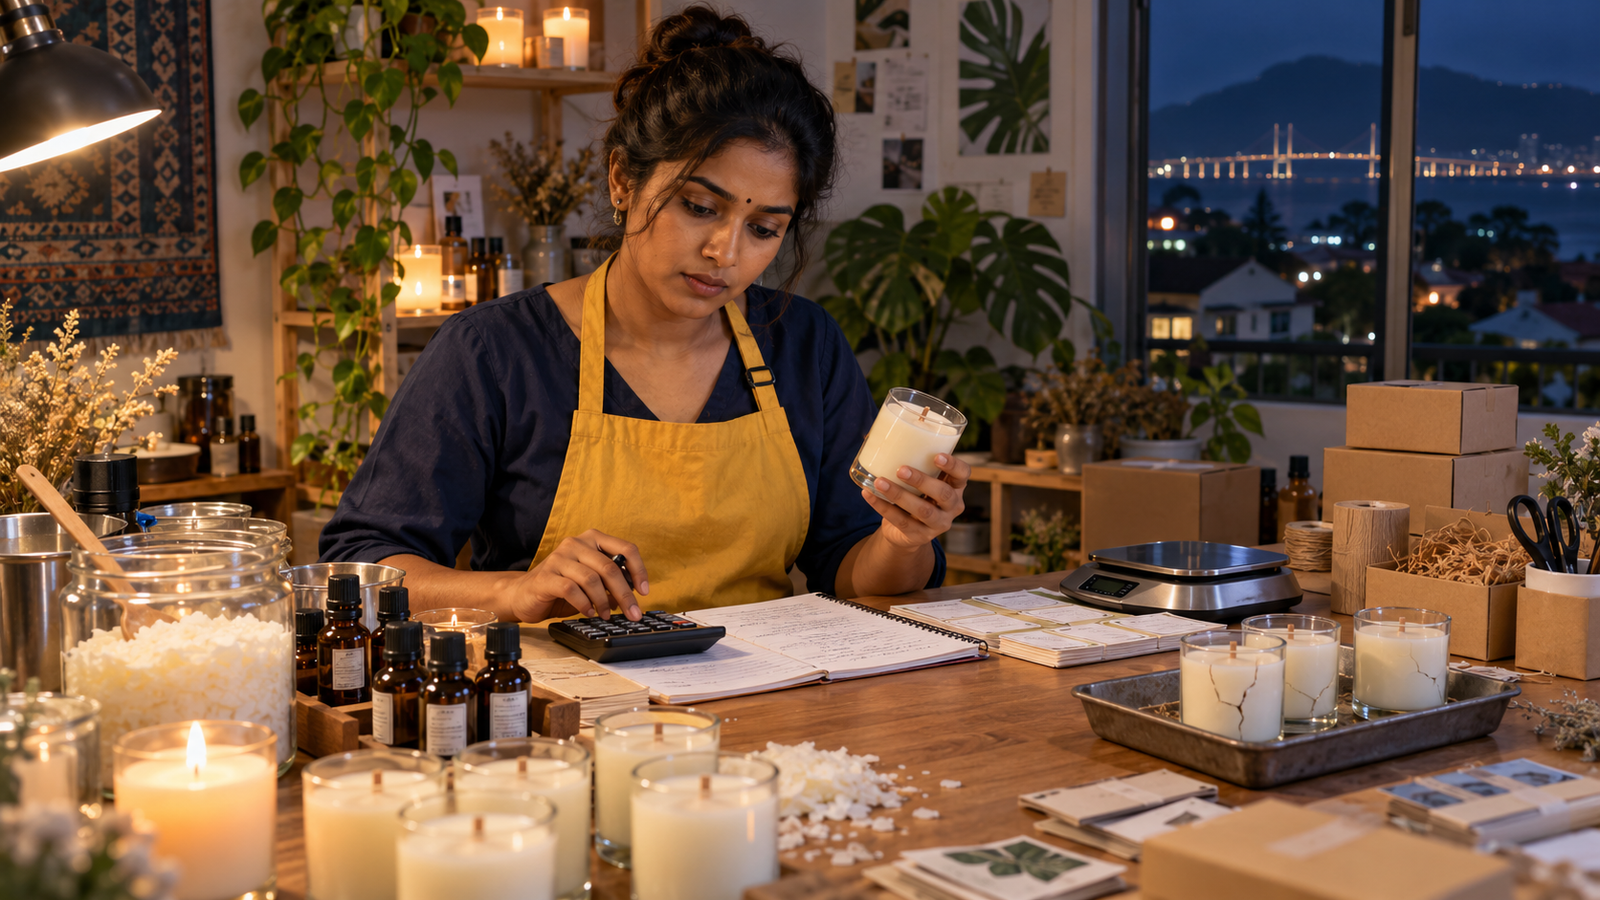

Sangeetha makes scented candles from a small studio in her Penang apartment. At a recent weekend market, her table was busy and the payment notifications kept arriving.
By Sunday evening, total sales had reached RM1,200. Friends congratulated her, and she went home believing it had been a very profitable weekend.
Two days later, she checked her bank balance and the cash remaining in her envelope. The amount felt far smaller than expected. She had recorded sales, but she had not recorded the full cost of each production batch.
Good sales do not automatically mean good profit
Sangeetha reconstructed the weekend using receipts and her notebook:
- Wax, jars, wicks and fragrance used in sold candles: RM528
- Market stall and transport: RM230
- Boxes, labels and paper bags: RM96
- Card and payment fees: RM20
- Samples and testers: RM36
- Twelve cracked or poorly finished candles from the same batch: RM120
Her total cash cost was RM1,030. That left RM170 before paying herself for her time.
She had spent seven hours producing and labelling the batch, three hours preparing the display, and seven hours at the market. At only RM5 per hour, those 17 hours were worth RM85.
Her real result was approximately RM85 in profit, not the hundreds of ringgit she first imagined.
Failed products belong in the batch cost
The biggest surprise was the twelve candles that never reached the market. Some had cracked tops, two had off-centre wicks, and several did not smell strong enough.
Sangeetha used to treat these as a separate mistake and ignored them when pricing the candles that sold. But the wax, jars and fragrance had still been paid for. The successful candles had to recover the cost of the failed ones.
She started giving every production run a batch number. For each batch, she recorded the quantity made, quantity accepted for sale, quantity rejected, material cost and hours spent. Within a month, she discovered that one fragrance caused more failed candles because it required a different pouring temperature.
That record helped her adjust the process, reduce waste and set a price that covered both successful and failed units.
Try this for seven days
If you make products in batches, test this simple routine for one week:
- Give every batch a date or simple reference number.
- Record the total material and packaging cost.
- Count finished, damaged and rejected units separately.
- Record preparation, production and selling hours.
- Divide the total batch cost by the number of products that can actually be sold.
Sales tell you what customers bought. Batch records tell you whether producing those items was worth your money and time.
Know the real profit behind every batch you make
Record materials, failed units and working time so strong sales can become healthy profit.