Alamat
Malaysia
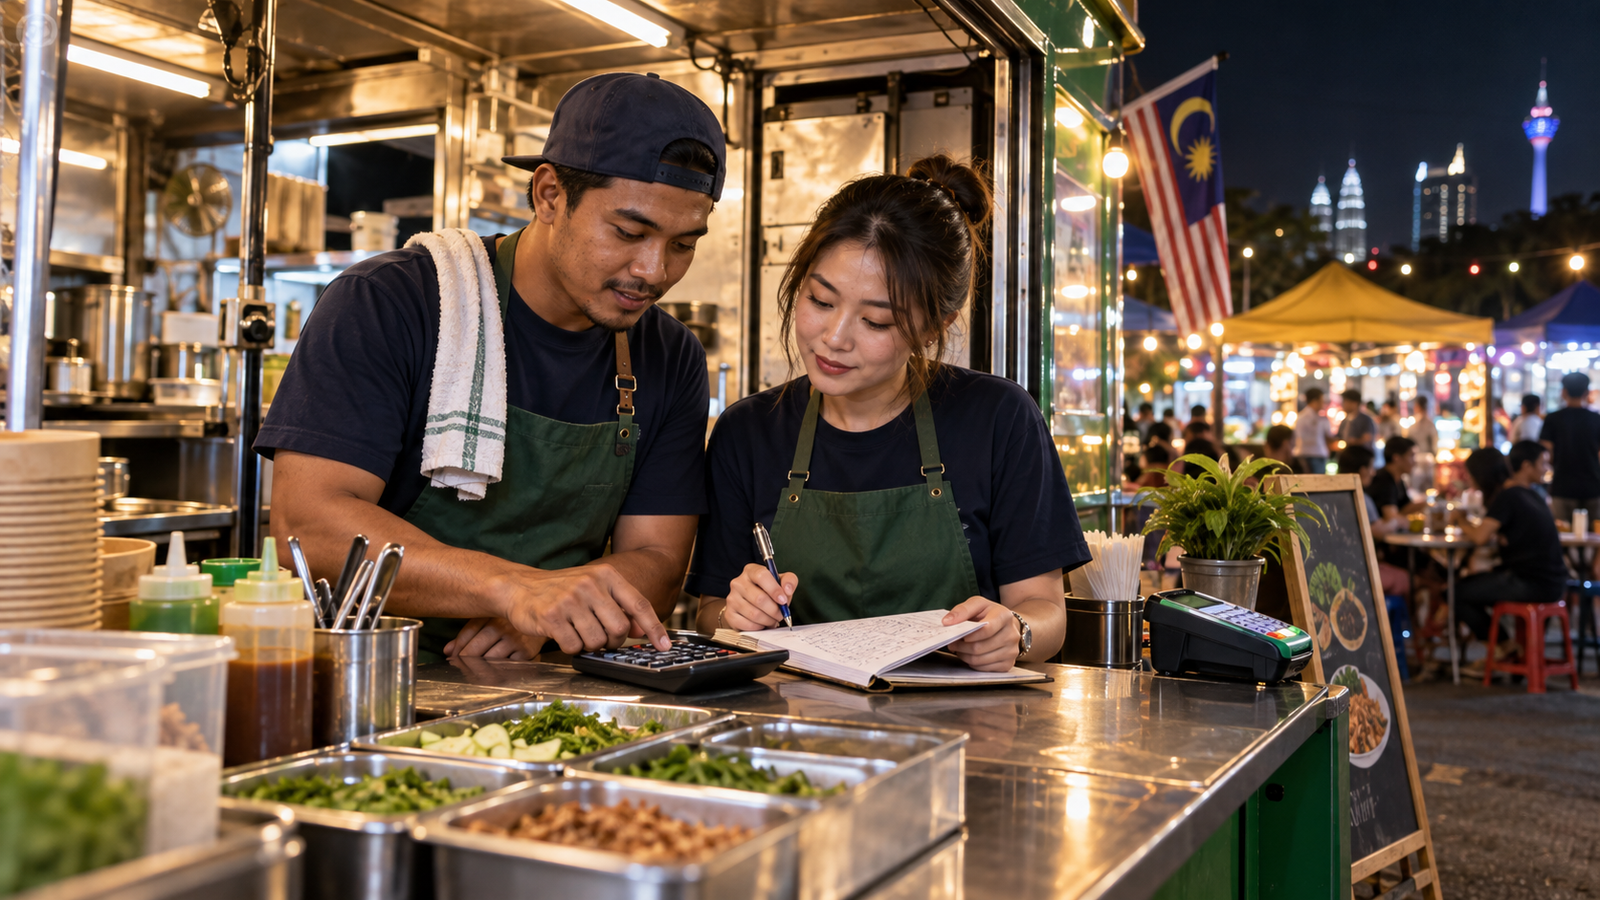

Every evening, Amir and Chloe served a long queue at their food truck. The payment terminal kept beeping, cash filled the drawer, and customers often told them the business looked successful. Yet every Monday morning, they struggled to find enough money to restock ingredients.
This is an illustrative story based on common situations faced by small Malaysian businesses. Their problem was not weak sales. It was the gap between money collected, bills paid and stock purchased.
RM18,000 in sales did not mean RM18,000 was available
In one month, the food truck recorded RM18,000 in sales. Ingredients and packaging cost RM8,200. Site rental, fuel and helpers cost RM4,300. They also spent RM2,100 on a new freezer and paid RM1,600 for supplies bought on credit the previous month.
On paper, sales looked strong. In the bank, however, only RM1,800 remained. Without a clear cash-flow record, Amir and Chloe kept wondering where the money had gone.
Three simple records gave them a clear answer
- Daily money in: cash, bank transfers and card payments were recorded separately.
- Daily money out: every ingredient purchase, small expense and supplier payment was written down.
- Upcoming commitments: rent, wages, instalments and supplier bills were listed before their due dates.
After four weeks, they saw that weekend sales were good, but large Monday restocking orders drained their cash. They reduced slow-moving menu items, ordered smaller quantities twice a week and kept equipment purchases in a separate plan.
A healthier business feels less uncertain
Their sales did not suddenly double. What changed was their control. They knew how much could be spent, which bills were coming and how much cash had to remain for the next trading day.
Try this for seven days
For the next seven days, record every amount that enters and leaves your business. At the end of each day, compare the recorded balance with your cash and bank balance. Any difference is a clue that deserves attention.